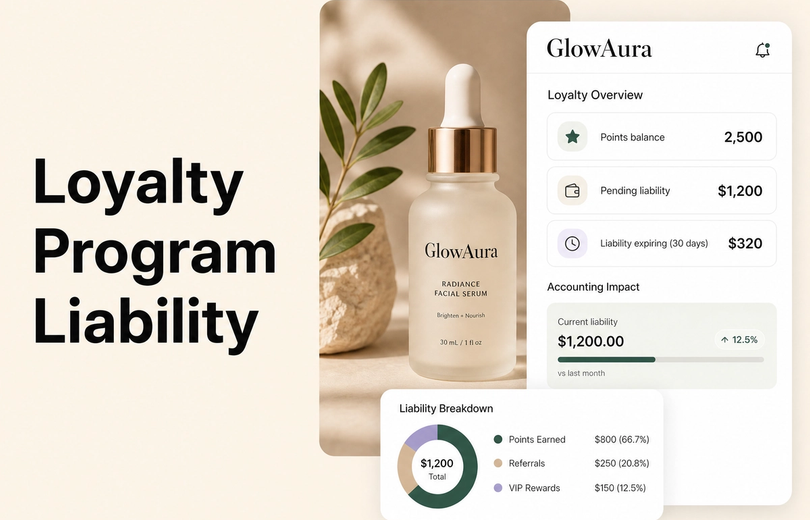
Can a loyalty points tax liability arise when your store gives customers points today for a reward they may use later? Yes, but the answer depends on whether you mean income tax, sales tax, or financial accounting, and on exactly how the reward works.
Short answer: A loyalty program can create tax questions and, in some cases, a tax liability for the brand. Issuing points does not, by itself, establish immediate taxable revenue. The applicable treatment depends on the reward structure, accounting method, and jurisdiction. Review the program terms, funding source, and records with an accountant before launch or a major change.
What does loyalty points tax liability mean?
| Question | What it concerns | Typical trigger | Who should review it |
|---|---|---|---|
| Income tax timing | When revenue or reward costs affect taxable income | Points issued, redeemed, or expired | Accountant or tax adviser |
| Sales tax | Tax charged on a discounted order or reward redemption | Discount applied at checkout | Sales-tax adviser |
| Financial accounting | How outstanding reward obligations appear in accounts | Expected future redemptions | Accountant or finance team |
Three different questions merchants often combine
Loyalty points tax liability is a catch-all phrase for three separate issues: income tax, sales tax, and financial accounting. A program can raise all three, but they do not follow the same rules.
Consider a customer who spends $100, earns points, then later receives $5 off an order. The original sale, future discount, and cost of fulfilling that reward can each raise a different question. The points balance alone does not answer any of them.
Points are not automatically taxable revenue
Issuing points does not, by itself, establish immediate taxable revenue. The applicable treatment depends on the reward structure, accounting method, and jurisdiction. In some circumstances, a merchant may need to allocate part of a sale to a future obligation. In others, the relevant issue may be when the business can deduct the reward cost.
That is why reporting a loyalty balance in your dashboard is different from deciding how it belongs on a tax return. If you are reviewing what counts as loyalty revenue, treat program reporting as an operational input, not a tax conclusion.
Why the reward promise matters
A Shopify loyalty program can offer fixed discounts, percentage discounts, free shipping, free products, or store credit. Those rewards may look similar to a customer, yet each creates different valuation, fulfillment, and sales-tax questions.
This is educational information, not tax, legal, or accounting advice. Bring the actual program terms to a qualified adviser before deciding how to account for points.
Myth: points are either always taxable or never taxable
The tax result depends on the transaction
There is no universal rule that issued points are always taxable immediately, or that loyalty rewards never affect tax. Tax treatment follows the transaction, not just the points balance.
For U.S. federal income tax purposes, the taxpayer’s accounting method, reward structure, whether the obligation is fixed, and applicable rules can all matter. The IRS has published an example involving a $1,000 television and 50 reward points. In that example, an applicable method may allow the retailer to defer the amount allocated to points instead of including the entire transaction value immediately.
That is an IRS example, not a Shopify rule or a universal answer for every rewards program.
Why accounting treatment does not settle the tax question
Financial accounting may record a liability for expected future rewards. Tax reporting may use different timing rules. A balance-sheet entry does not automatically create a current deduction, and a deferred-revenue figure does not automatically determine taxable income.
The IRS and taxpayers have also disagreed over whether loyalty reward costs are deductible when points are earned or only when rewards are redeemed, as discussed by the University of Illinois Tax School.
Keep the finance question separate from the tax question. Your accounting team may need both answers, but one does not automatically supply the other.
When can loyalty points be treated as deferred revenue for tax purposes?
The basic deferred-revenue idea
A points program can include two promises in one customer transaction. The customer receives today’s product, plus an option to claim a future reward if they meet the redemption conditions.
Financial accounting often values that future obligation using the estimated value of points and the likelihood that customers will redeem them. A public-company filing explains that deferred revenue can reflect estimated retail value and expected breakage, meaning points expected to go unused, with changes in redemption behavior affecting the liability reported in its accounts.
This does not mean every loyalty program must defer revenue for tax purposes. It means outstanding points can require a formal analysis.
Tax deferral versus a deductible reward cost
Under qualifying circumstances, U.S. tax rules may permit a trading-stamp or premium-coupon method that defers an amount allocated to points. Other programs may focus on when the reward cost becomes deductible, including whether the liability is fixed and whether economic performance has occurred.
Those routes can produce different timing. A merchant might have a financial-accounting liability for outstanding points while taking a tax deduction later. Another merchant may qualify for a tax method that allocates part of the original sale to future redemptions.
The relevant facts include what customers receive, whether the reward is a discount or product, when it expires, how it is funded, and how reliably redemption can be estimated.
Breakage, redemption, and expiration
Breakage means points that customers are expected never to redeem. It affects financial estimates because a promise that is unlikely to be claimed may carry a different value than one customers use consistently.
A public-company filing reported that a 10% change in redemption rate or retail value per point affected earnings by about $1.4 million. That is a public-company example, not a benchmark for Shopify brands. The useful lesson is that changes in assumptions can materially alter an accounting estimate.
Expiry rules, point value, minimum redemption thresholds, and reward catalog changes can all affect expected redemption. Preserve the history of those changes rather than overwriting old settings.
How does sales tax work when customers redeem loyalty rewards?
| Reward type | What the customer receives | Tax question to ask | Evidence to retain |
|---|---|---|---|
| Fixed or percentage discount | Money off an order | Does the discount reduce the taxable selling price? | Order total, discount value, tax charged |
| Store credit redemption | An equal discount against an order | Which credit rail and funding source apply? | Redemption record and checkout receipt |
| Free product | One product discounted to zero | Is it a promotional item or taxable sale? | Product record and final order |
| Free shipping | Shipping charge removed | Is shipping taxable for this order? | Shipping rate and tax calculation |
Store-funded discounts
Shopify states that discounts are applied to the order subtotal before applicable tax in its standard discount flow. That describes checkout behavior, not the final tax rule for every jurisdiction.
A merchant-funded points reward may reduce the customer’s taxable selling price in some places. New York’s loyalty-card guidance provides one example: a store-funded discount reduced the taxable price in the state’s example, as explained in the New York tax bulletin.
Verify the rule for each location where you have sales-tax obligations.
Third-party or manufacturer-funded discounts
Funding can change the analysis. If a supplier, manufacturer, marketplace, or other third party reimburses the merchant for the discount, the jurisdiction may treat the transaction differently.
New York’s bulletin gives the contrasting example: a reimbursed manufacturer discount left sales tax due on the full selling price under its stated rules. Do not apply that result nationwide. Use it as a reminder to document who pays for each reward.
A points redemption can work operationally like a discount code at checkout while still requiring a separate legal analysis of its funding source.
Free products and free shipping
Free-product rewards require their own review. The customer may see a zero-dollar item, but local rules may treat it as a promotional giveaway, a discounted sale, or something else.
Free shipping is separate again. Shipping taxability can vary by jurisdiction, product category, and how the charge appears on the order.
Mage supports fixed, percentage, flexible, free-product, free-shipping, and store-credit redemption models. Its loyalty store-credit mode is an internal Mage ledger, not automatically Shopify-native store credit. Review Shopify-native store credit versus loyalty-app store credit before assuming two credit types have the same treatment.
Why jurisdiction differences matter more than the points balance
State and local sales tax differences
A points balance is a customer record. Taxability depends on the transaction behind the redemption.
Sales-tax treatment can vary based on customer location, product type, reward type, discount funding, shipping charge, and recordkeeping requirements. New York’s distinction between store-funded and reimbursed discounts is a concrete example, but it is not a nationwide rule.
Add these factors to the market-by-market checklist in the next section, especially when expanding into new states or changing nexus exposure.
Federal income tax versus state income tax
A federal income-tax method does not settle state income-tax treatment. A sales-tax conclusion does not settle income-tax timing. The same reward may need review from more than one angle.
High-value, lower-frequency categories can also need careful reward valuation. For example, jewelry loyalty programs may rely more heavily on substantial tier perks, store credit, or free shipping than frequent-purchase programs.
International VAT and GST questions
VAT and GST systems may apply separate rules to vouchers, coupons, discounts, gift certificates, and loyalty rewards. Do not use a U.S. state example to decide treatment in another country.
Shopify Markets and tax settings can help calculate and display taxes, but they do not replace jurisdiction-specific advice. Add each new market to the review process before activating rewards there.
“Cannot say enough good things about the team at Mage Loyalty, one of the absolute best organizations we have ever worked with, full stop! So glad we connected with them, completely redid our loyalty program, new concepts, use of loyalty, increasing user engagement, showing us where we were not valuing our best customers, just WOW, amazing team!”

Read the West Coast Goalkeeping case study →
What Shopify merchants should document before launch
| Program element | Example | Why it matters | Record to export or retain |
|---|---|---|---|
| Earning rule | Points per dollar spent | Establishes reward economics | Rule settings and launch date |
| Reward type | Percentage discount or free product | Changes the tax question | Reward configuration |
| Funding source | Merchant-funded reward | May affect sales-tax treatment | Supplier or funding agreement |
| Expiry policy | Points expire after a set period | Affects breakage estimates | Terms and change log |
| Refund treatment | Points reversed after refund | Keeps records aligned to orders | Refund and activity logs |
Program economics
Document how customers earn points, their effective reward rate, redemption thresholds, maximum redemptions, eligible products, and expiry policy. Record whether the program offers a fixed discount, percentage discount, flexible discount, free product, free shipping, custom reward, or store credit.
Use the same working file you use to calculate a loyalty reward rate to show the economic value behind each reward.
Redemption and refund behavior
Retain sample orders showing the original price, reward applied, taxable subtotal, tax charged, refund outcome, and final accounting entry. Track issued, redeemed, expired, and outstanding points, along with cancellations, refunds, and reactivated reward codes where relevant.
Mage can issue discount codes for reward redemptions, while free-product rewards can apply a discount to one unit. Mage also reverses points after refunds and adjusts VIP progress, with activity recorded against the customer. That keeps program records aligned with order changes, but it does not determine the tax treatment.
Records an accountant will need
Keep program terms, reward configurations, checkout examples, tax settings, refund logic, historical redemption data, and dates for changes to point value, expiry rules, or reward eligibility.
Also identify who funds each reward. A merchant-funded $10 discount and a reimbursed $10 discount can require different sales-tax analysis, even when the customer sees the same checkout reduction.
When should you involve an accountant?
Involve an accountant before launch or a major change if you expect substantial redemptions, operate across multiple states or countries, offer high-value rewards, receive third-party reimbursement, or introduce free products, cashback, memberships, or store-credit rewards.
A review is also appropriate before changing point value, expiry rules, reward thresholds, the catalog, funding arrangements, or accounting method. Do the same before expanding into a new market.
Bring the checklist records above, plus sample orders and any redemption or breakage history. Ask when revenue should be recognized, whether a premium-coupon or trading-stamp method is available, when reward costs are deductible, whether redemption reduces the taxable selling price, and how expired points should be handled.
FAQ
Are loyalty points taxable to the brand?
Loyalty points are not automatically immediate taxable income to the brand, but they can create income-tax, deduction, deferred-revenue, and sales-tax questions. The result depends on the reward structure, accounting method, funding source, redemption event, and jurisdiction.
Are loyalty points taxable to customers?
Loyalty points can have different tax treatment for customers than for merchants. Ordinary purchase rewards may differ from referral payments, prizes, employee benefits, business-related rewards, or anything convertible to cash. Customers with unusual or high-value rewards should ask a qualified tax professional.
When are loyalty points treated as deferred revenue?
Loyalty points may be treated as deferred revenue in financial accounting when they represent an expected future reward obligation. Tax treatment can use different recognition and deduction rules, so an outstanding-points liability on financial statements does not automatically determine the amount or timing reported on a tax return.
Does redeeming loyalty points reduce sales tax?
Redeeming loyalty points may reduce sales tax where a store-funded discount reduces the taxable selling price under local rules. Shopify applies standard discounts before tax, but third-party reimbursement, product type, shipping treatment, and jurisdiction can change the result.
Do expired loyalty points create taxable income?
Expired loyalty points can affect accounting estimates and potentially tax timing, but they do not create immediate taxable income under one universal rule. The treatment depends on program terms, the applicable tax method, the jurisdiction, and whether the points were previously treated as part of a deferred obligation.
When should I ask an accountant about my loyalty program?
Ask an accountant before launch and before major changes to the program’s economics. Review is especially useful for multi-jurisdiction programs, third-party-funded discounts, high-value rewards, free products, cashback, significant outstanding balances, and changes to expiry, redemption value, or funding arrangements.
A loyalty program needs a tax review when its terms create a meaningful future obligation or affect checkout pricing across jurisdictions. Document the mechanics before launch, keep transaction-level records, and let your accountant determine the treatment that fits your business and markets.

Kris is the co-founder of Mage Loyalty. I spend most days talking to merchants, and making sure our customers get real results. If you run a Shopify store or Agency we should chat!